Blog / Used and Trade-Ins

Blog

All Used and Trade-Ins Service and Maintenance Silverado Trucks Suburban and SUVs
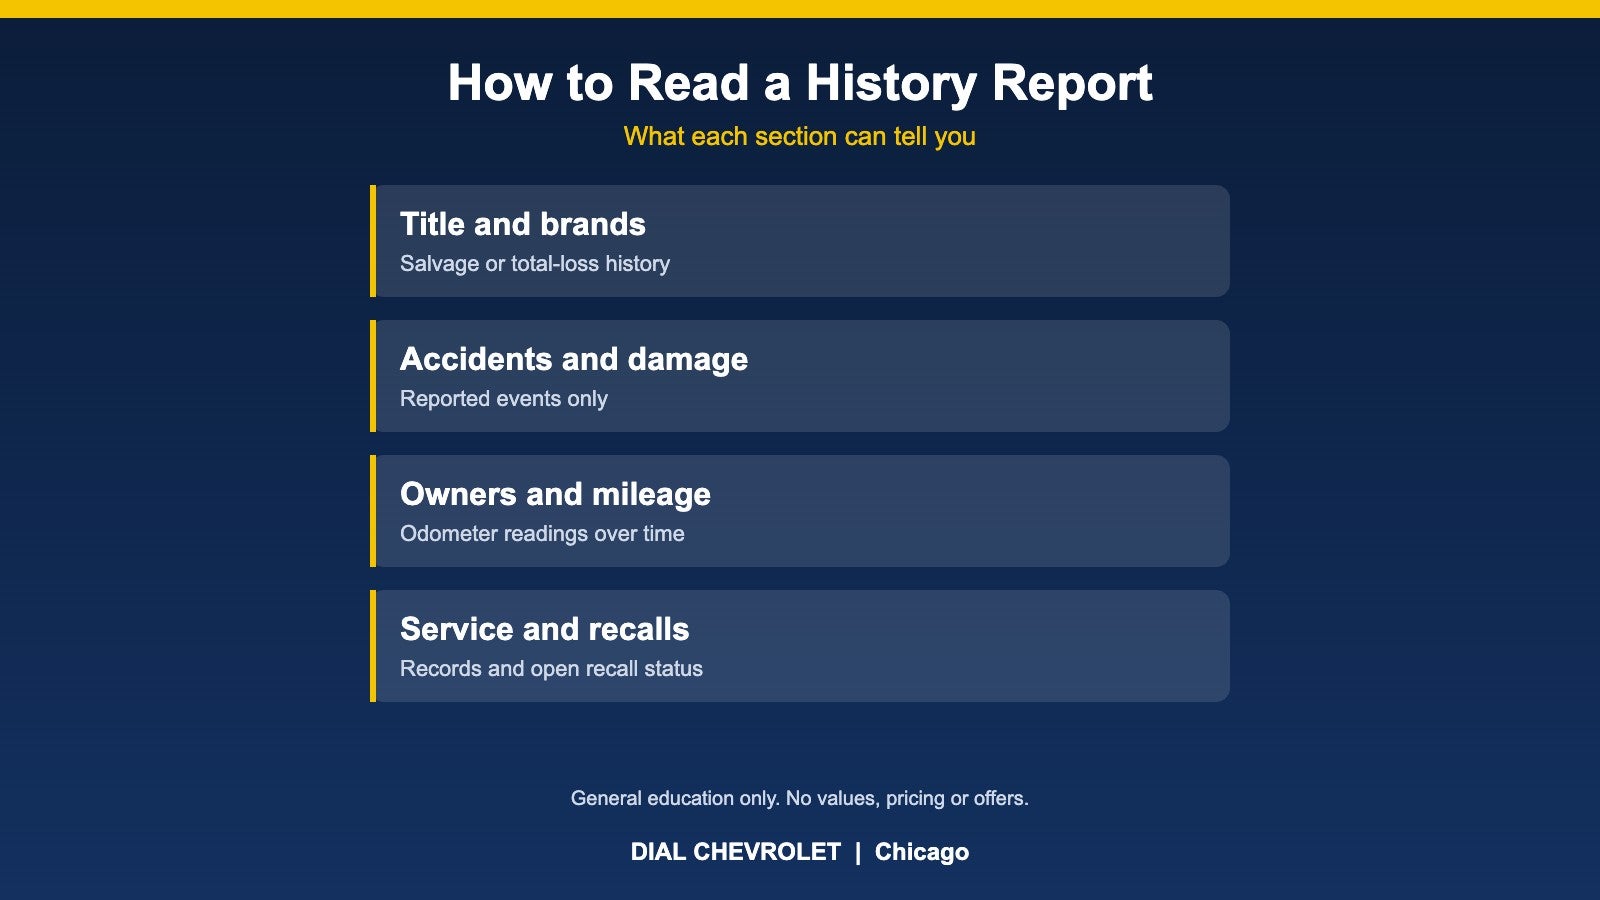
Graphic listing the main sections of a vehicle history report

How to Read a Used Car History Report

Short answer: a vehicle history report is a record of what has been reported about a used vehicle: title status, accidents or damage, owners, odometer readings, service entries and recalls. It is a helpful starting point, but it only covers what was reported, so it should be paired with an in-person inspection. Where the Report Comes From The Federal Trade Commission recommends getting a vehicle history report before buying a used car and notes that reports may include ownership history, accidents, repair records and whether the vehicle was ever declared salvage. The FTC does not endorse any specific provider. The federal National Motor Vehicle Title Information System (NMVTIS) is one source of title and brand data, and commercial report providers combine several sources. Reports differ in layout and in what they include, so the sections below are a general guide. Title and Brand Status Read this first. A brand such as salvage or total loss means the vehicle was declared a loss at some point and may need a closer look. Without knowing the brand history, a buyer may pay more than a vehicle is worth or buy one that was not properly repaired. A clean title only means that no brand was reported. Accidents and Damage Look at whether any accident or damage events were reported and how they are described. Not every collision is reported, and a report cannot show the quality of a repair. If you see a reported accident, ask for repair records and point it out to the inspecting mechanic. Our used SUV inspection checklist shows what to check in person. Owners, Registration and Use The report may show how many owners a vehicle has had and where and when it was titled. A report generally cannot show exactly how a prior owner used the vehicle. Frequent ownership changes are worth asking about, but they are not proof of a problem on their own. Odometer Readings Readings recorded at title transfers, inspections or service visits should rise over time. A reading that drops or stays unusually flat can be a sign of an error or a rollback, and is worth questioning. Service Records and Recalls Service entries can support the story a seller tells about maintenance, but many routine services never appear on a report. Check open recalls by VIN as well; our recall check guide explains how. What a Report Cannot Tell You Reports do not measure wear and tear, and they can be incomplete. Treat the report as one input, then add a test drive and an independent inspection. If you are comparing vehicles, our total cost of ownership guide can help with the bigger picture. Talk to the Dial Chevrolet Team You can browse used inventory or contact us to ask what documentation is available for a specific vehicle. Sources Federal Trade Commission: Used cars NMVTIS: Understanding a vehicle history report Chase: What is a vehicle history report? Published by Dial Chevrolet, 6603 S Western Ave, Chicago. General education only. No vehicle values, pricing, report-provider endorsements or offers are stated.
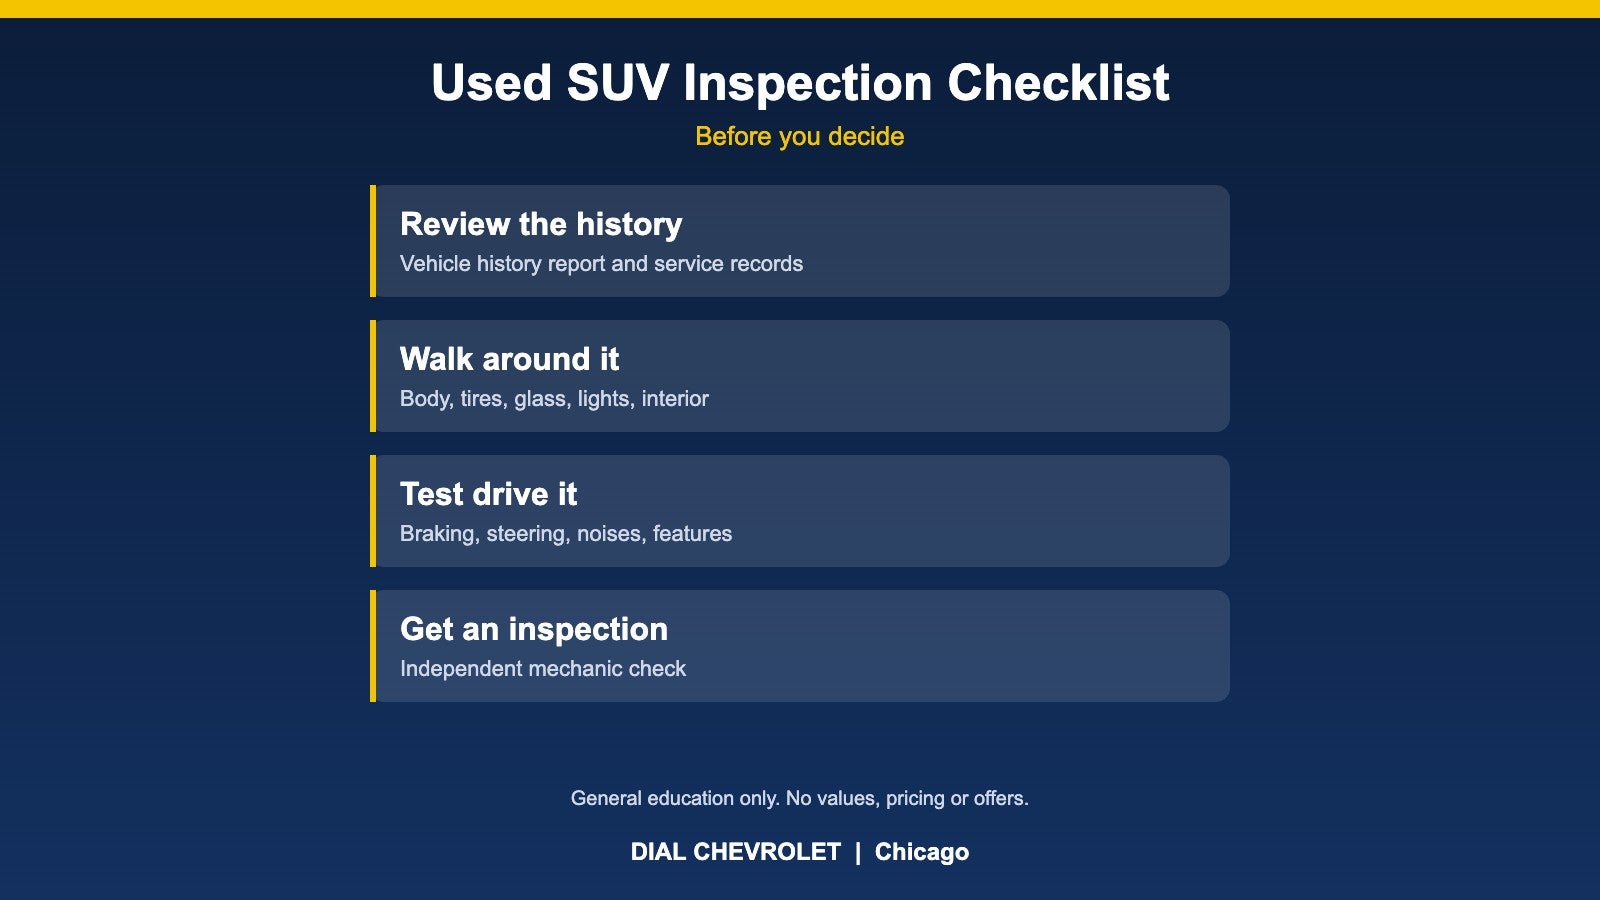
Checklist graphic for inspecting a used SUV before buying

Used SUV Inspection Checklist for Buyers

Short answer: before buying a used SUV, review its vehicle history report and service records, inspect it carefully in person, take a thorough test drive, and have an independent mechanic perform a pre-purchase inspection. Each step catches different problems, so it helps to do all of them. Start With the History Ask for a vehicle history report, which can show ownership changes, reported accidents, service entries and open recalls. Reports are a useful starting point but are not guaranteed to be complete, so treat them as one input. Service records matter too: be cautious when maintenance is claimed but cannot be documented. Walk Around the Exterior Look for mismatched paint, uneven gaps between panels or signs of past repairs. Check tires for even wear and ask how old they are. Inspect glass, lights and mirrors for damage. In Chicago, look underneath and along the lower body for rust, since road salt is hard on metal. Our road salt corrosion guide explains why. Check the Interior and Features Test every window, lock, seat adjustment, climate control setting and the infotainment system. Look for water stains, musty smells or worn areas that do not match the mileage. Confirm all warning lights turn on at start-up and go off. A light that stays on needs explaining; see our check engine light guide. For a three-row SUV, check that the second and third rows fold and latch properly, and that child-seat anchors work if you need them. Take a Real Test Drive Drive on a mix of roads that includes bumps, a highway stretch and some stop-and-go. Listen for unusual noises, feel for pulling or vibration, and test the brakes firmly in a safe place. If you plan to tow, ask about the vehicle's towing equipment and confirm capability for that exact vehicle in its documentation rather than assuming it. Get a Pre-Purchase Inspection Automotive guides consistently recommend an independent inspection by a qualified mechanic before you finalize a purchase, because many used vehicles are sold as-is and a technician can spot issues a walk-around may miss. An inspection usually covers the engine, transmission, suspension, brakes and underbody. It will not catch everything, but it improves your odds. Private sellers may be less willing to allow one, which is itself something to weigh. Compare the Total Picture Condition is only part of the decision. Think about ownership costs as well; our total cost of ownership guide and the new vs. used comparison can help. Talk to the Dial Chevrolet Team You can browse used inventory, start a trade-in request, or contact us to ask what documentation is available for a specific vehicle. Sources Edmunds: What to look for when buying a used car CarGurus: The ultimate used car buying checklist RepairPal: Pre-purchase inspection Published by Dial Chevrolet, 6603 S Western Ave, Chicago. General education only. No vehicle values, pricing, warranty terms or offers are stated.

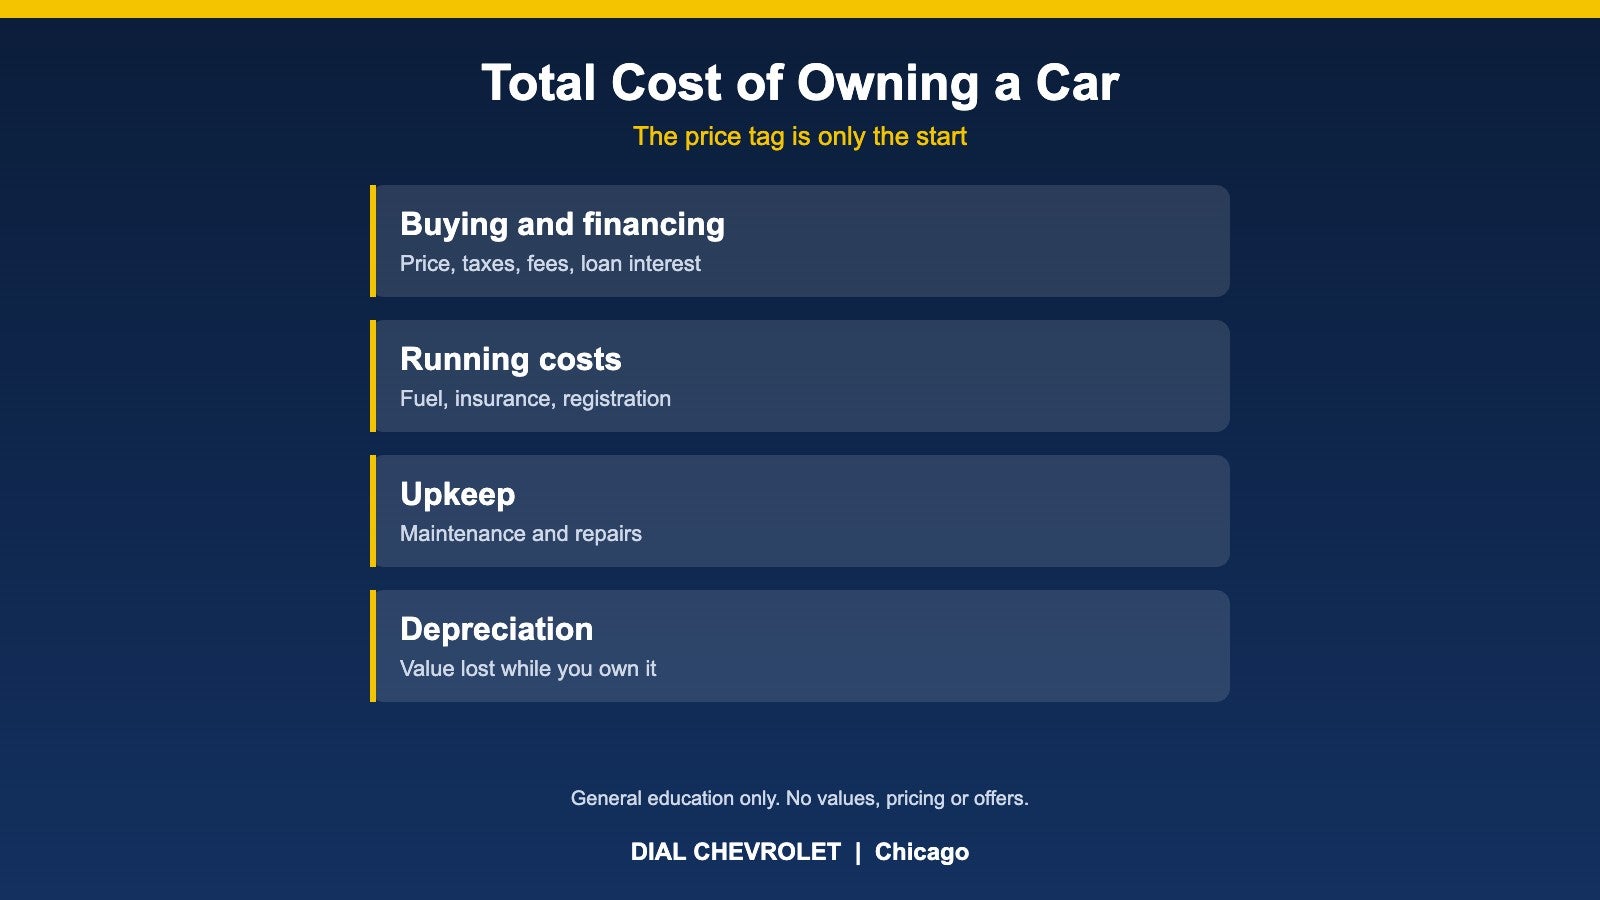
Graphic listing the main costs of owning a car

Total Cost of Owning a Car: What to Count

Short answer: the total cost of owning a car is the purchase price plus everything you pay or lose while you keep it: financing, taxes and fees, insurance, fuel, maintenance and repairs, and depreciation. Looking at all of them together gives a more realistic picture than the monthly payment alone. The Main Cost Categories Consumer guides from sources such as Edmunds, Kelley Blue Book and AAA describe ownership cost in a similar way. The common pieces are: Buying and financing: the price, sales tax, title and registration fees, and loan interest if you finance. Insurance: premiums vary by vehicle, driver and location, so a quote for the specific model is more useful than an average. Fuel: depends on fuel economy, driving habits and fuel prices. Maintenance and repairs: routine service plus repairs that come up as the vehicle ages. Depreciation: the value a vehicle loses over time. It is not a bill you pay, but it affects what you get when you sell or trade, and it is often described as one of the largest ownership costs. How to Build Your Own Estimate List the vehicles you are considering, including a new and a used option. Request insurance quotes for each specific model. Estimate fuel from your typical weekly driving and the vehicle's rated fuel economy. Check the maintenance schedule for what service is due and when. Our maintenance schedule guide is a starting point. Consider how long you plan to keep the vehicle, since depreciation and repair costs change with ownership length. Fixed and Changing Costs Loan payments and insurance premiums tend to be predictable. Fuel, maintenance and repairs change with how much you drive and how the vehicle ages. In Chicago, winter driving and road salt can add wear, so it is sensible to keep some room in a budget for upkeep. See our guides on road salt corrosion and winter preparation. New or Used A newer vehicle usually has more of its value left to lose, while an older vehicle may need more repairs. Neither is always cheaper over time. Our new vs. used comparison and buying vs. leasing guide cover the tradeoffs without quoting prices. Talk to the Dial Chevrolet Team You can browse new and used inventory, or contact us with questions. Any payment or pricing question is best answered by the dealership directly for the specific vehicle. Sources Edmunds: True Cost to Own Kelley Blue Book: Total cost of ownership Chase: How to calculate the total cost of car ownership Published by Dial Chevrolet, 6603 S Western Ave, Chicago. General education only, not financial advice. No vehicle values, pricing or offers are stated.

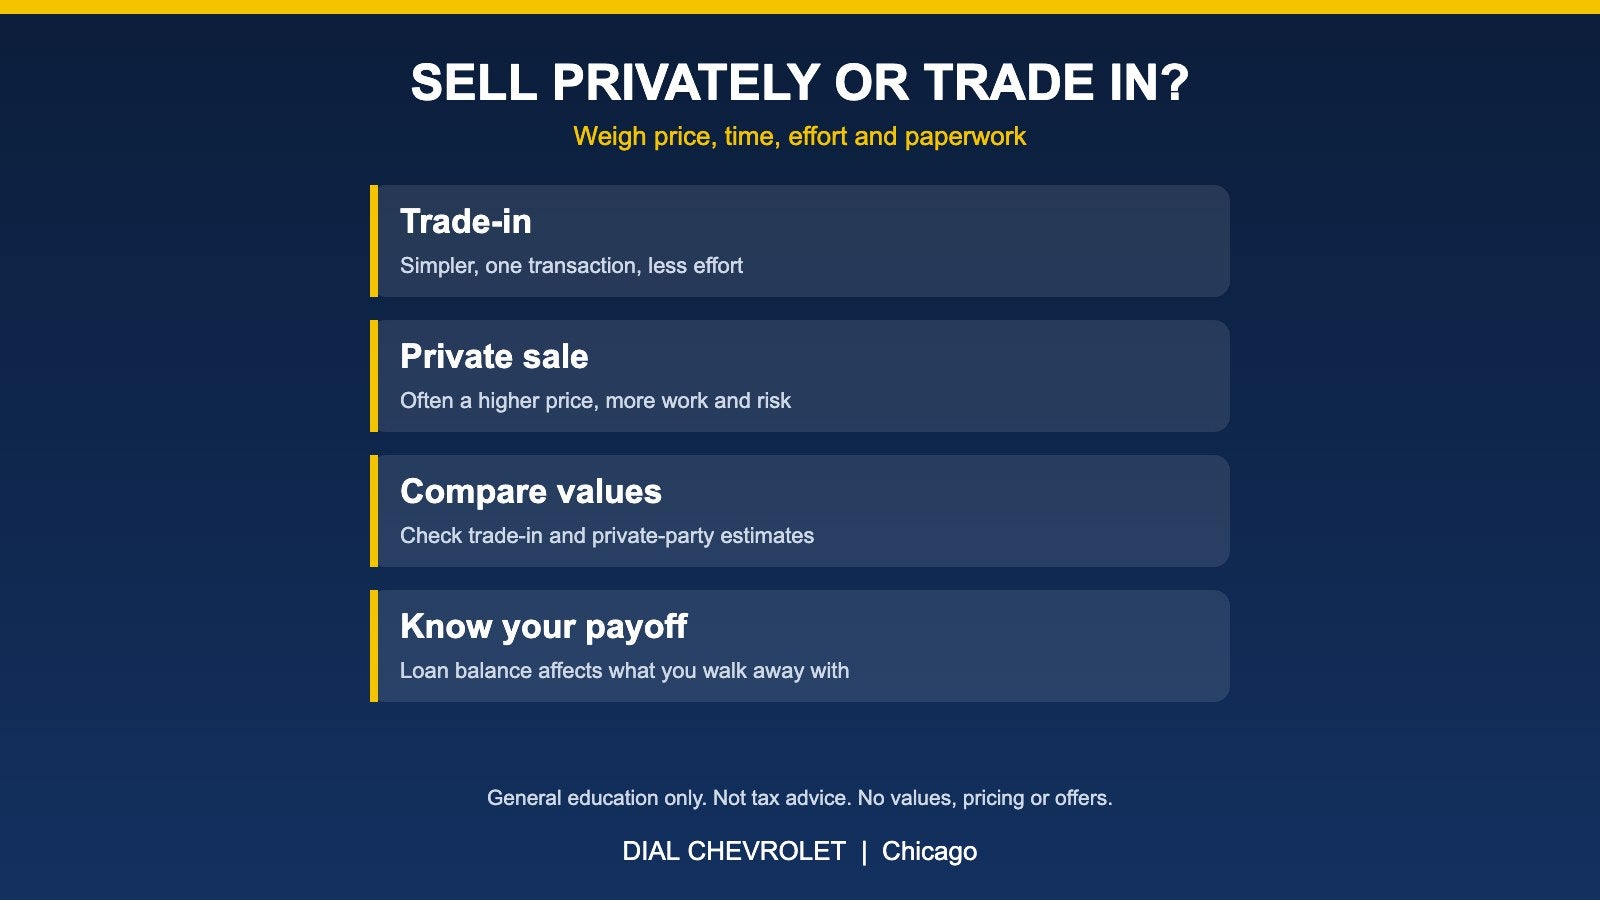
Checklist graphic comparing selling a car privately with trading it in

Sell Privately or Trade In? What to Weigh

Short answer: a trade-in is usually simpler and faster, while a private sale often brings a higher price but takes more time, effort and risk. The right choice depends on how you value convenience against money, and on whether you still owe on the vehicle. What a Trade-In Offers With a trade-in, you handle the old vehicle and the next purchase in one transaction at one dealership. There are no listings, calls or test drives with strangers, and the dealership handles the title paperwork. The trade-off is that dealer offers are generally lower than what a private buyer might pay. What a Private Sale Offers Selling it yourself can bring a higher price, but you take on the work. That includes photos, listing, answering messages, meeting buyers, taking payment and completing the title and registration steps. Consumer guides also warn about haggling, no-shows and scams in private sales, so safety and payment method matter. Compare Real Numbers First Look up both a trade-in estimate and a private-party estimate for your exact vehicle, mileage and condition from a recognized valuation site, then compare the gap. Remember that an online estimate is not an offer, and condition matters. For a checklist of what to gather, see our trade-in preparation guide. If You Still Owe on the Vehicle Either way, your loan payoff has to be settled before the title can transfer. Our guide to trading in a car with a loan explains positive and negative equity. A Note About Sales Tax Many states give a tax advantage on a trade-in, because the trade-in value can reduce the taxable price of the next vehicle. Illinois Department of Revenue rules address trade-in allowances on dealer purchases, but there are limits and exceptions and the rules change. Check with the Illinois Department of Revenue or a tax professional about your own situation. This article is not tax advice. Which Option Fits You? A trade-in may fit if you value speed, want one transaction, and are replacing the vehicle right away. A private sale may fit if you have time, are comfortable with the process, and the price gap matters to you. Talk to the Dial Chevrolet Team You can start a trade-in valuation request, browse used inventory, or contact us with questions. A valuation request is not a guaranteed offer. Sources Chase: Trading in a car vs. selling Cars.com: Pros and cons of a trade-in vs. private sale Illinois Administrative Code: Traded-in property (86 Ill. Adm. Code 130.425) Published by Dial Chevrolet, 6603 S Western Ave, Chicago. General education only, not tax or legal advice. No vehicle values, pricing or offers are stated.

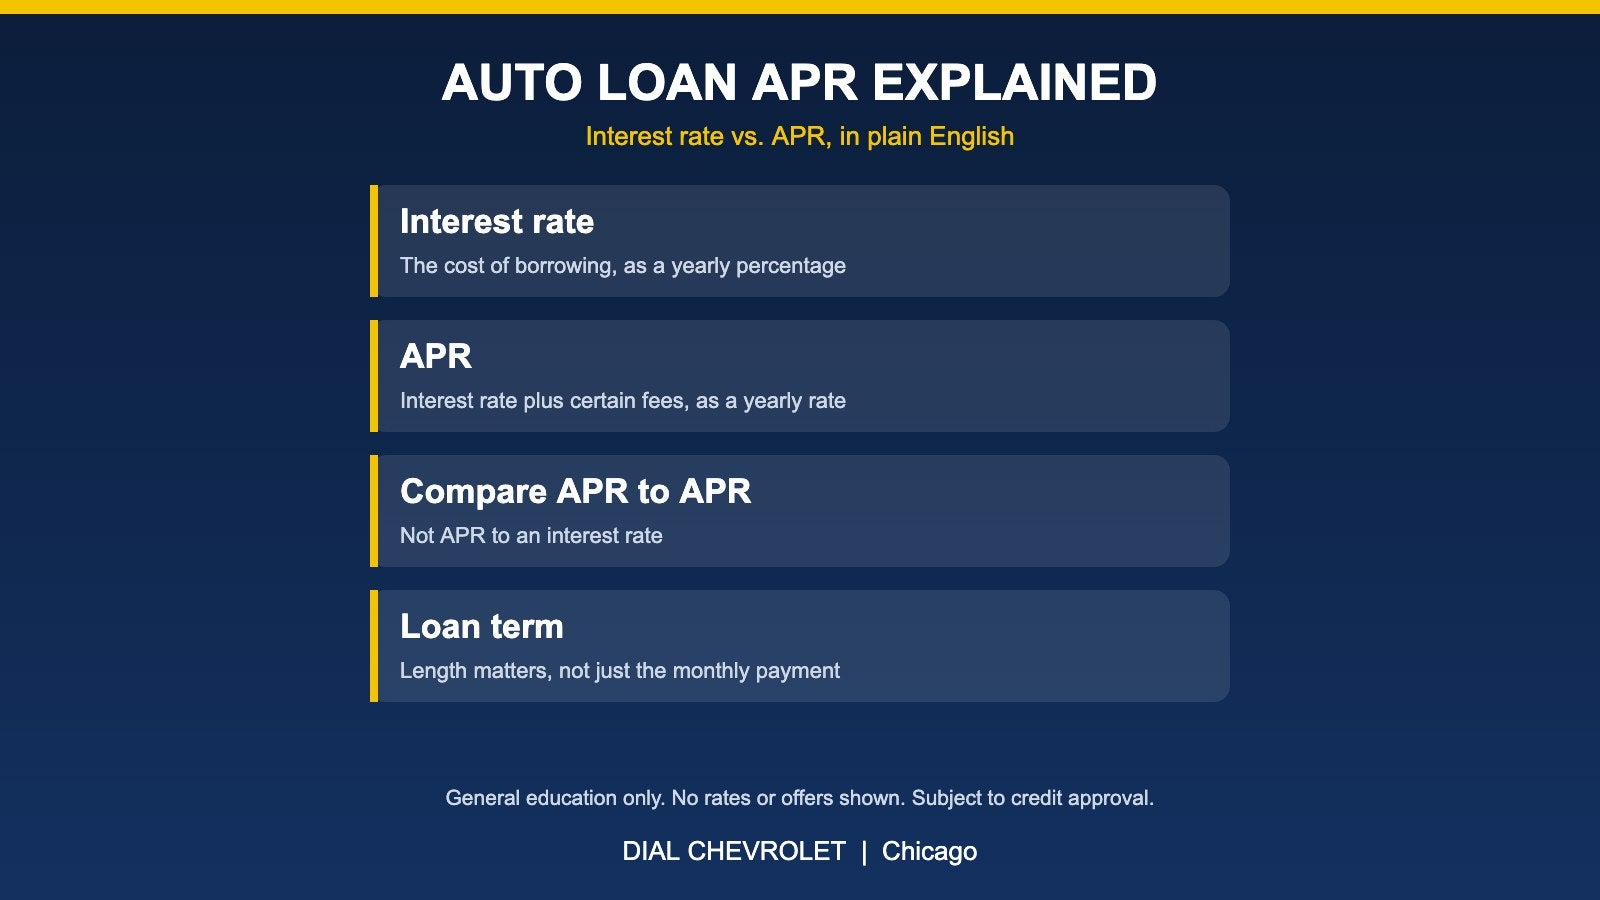
Graphic explaining interest rate versus APR, comparing APR to APR, and why loan term matters when financing a vehicle

Auto Loan APR Explained in Plain English

Short answer: an auto loan's interest rate is the cost of borrowing, and the APR (annual percentage rate) is a broader yearly figure that adds certain fees. When you compare financing offers, compare APR to APR, and look at the loan term and total cost as well as the monthly payment. Interest rate vs. APR The Consumer Financial Protection Bureau (CFPB) explains that the interest rate is the cost you pay each year to borrow money, expressed as a percentage, and it does not include loan fees. The APR reflects the interest rate plus certain fees charged with the loan, also as a yearly percentage. Because the two are not the same, the CFPB says to make sure you compare APRs to APRs and not APRs to interest rates. What else shapes the cost of a loan Loan term: a longer term can lower the monthly payment but usually means more interest over the life of the loan, so look at the total cost, not just the payment. Down payment: the CFPB notes that a larger down payment reduces the amount you borrow and can lower the total cost of the loan. A trade-in can count toward a down payment. Fixed vs. variable rate: with fixed-rate financing the rate does not change over the life of the loan, so the payment stays the same. Add-ons: products such as extended warranties or debt cancellation are optional and affect the amount financed. Ask what each one costs and whether it is required. Negative equity: if you owe more on your current vehicle than it is worth, the CFPB warns that rolling that balance into a new loan can make the new loan more expensive. Our guide to trading in a car with a loan goes through this. Where financing can come from The CFPB describes two common routes: dealer-arranged financing, where the dealership sends your application to one or more lenders, and a loan from a bank or credit union you arrange yourself. The CFPB's advice is to shop around and compare offers, including any quote you already have, so you can see what fits your budget. Federal law also requires lenders and dealers to give you Truth in Lending disclosures, including the APR and finance charge, before you sign. Questions to ask before you sign What is the APR, and what fees are included in it? What is the loan term, and what is the total amount I will pay over that term? Is the rate fixed? Are any add-on products included, and are they optional? Is there a penalty for paying the loan off early? This article does not list rates, payments or offers. Any financing terms depend on the lender, your credit and the specific vehicle, and are subject to credit approval. See our guide to buying vs. leasing a Chevrolet and the comparison of new vs. used Chevrolet for more on how to choose. Talk to the Dial Chevrolet Team To ask about financing options, contact the dealership. You can also browse new inventory, browse used inventory or value your trade-in. Our trade-in preparation guide can help you get ready. Sources CFPB, What is a loan annual percentage rate (APR)? CFPB, Auto loans key terms CFPB, Shopping for your auto loan Published by Dial Chevrolet, 6603 S Western Ave, Chicago. This article is general education only and is not financial or legal advice. It does not include any rates, payments, pricing or offers. Financing is subject to credit approval.

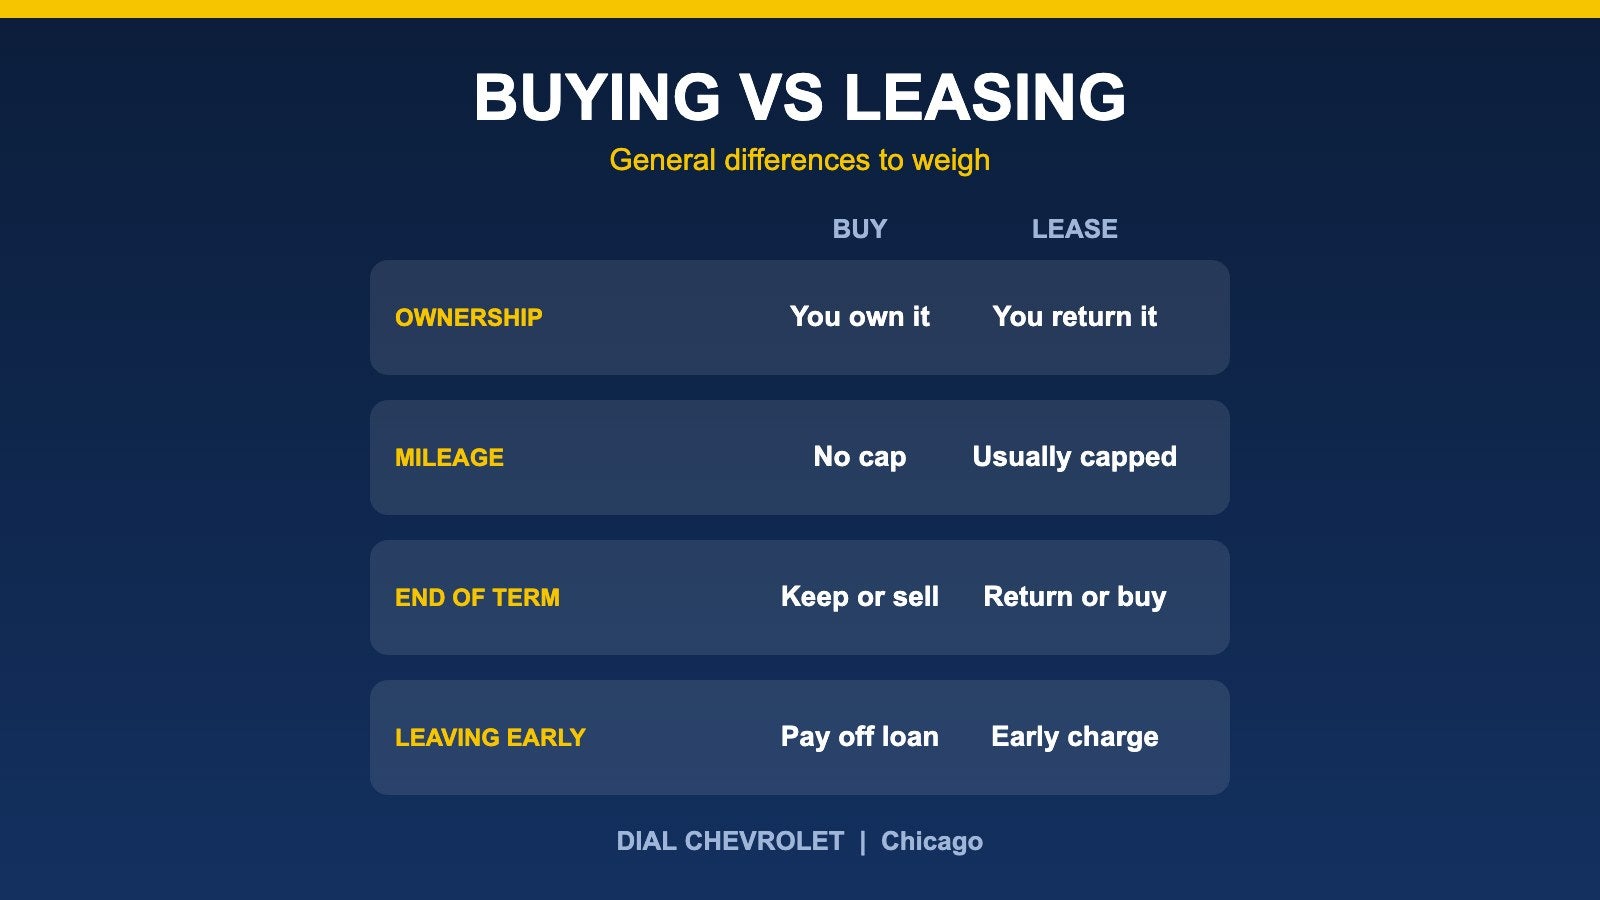
Buying vs leasing graphic: ownership, mileage, end of term and leaving early

Buying vs Leasing a Chevrolet: Which Fits How You Drive?

Short answer: Buying means you own the vehicle once the loan is paid and can drive as many miles as you like. Leasing means paying to use a vehicle for an agreed number of months and miles, then returning it. Neither is better for everyone: the right choice depends on how much you drive, how long you keep vehicles, and how you want to handle the end of the term. This guide covers general differences only and does not list prices, payments or offers. How buying and leasing differ Ownership: The Consumer Financial Protection Bureau (CFPB) explains that when you buy, you own the vehicle once your payments are made. A lease is an agreement to use a vehicle for a set number of months and miles, and unless the lease includes a purchase option you return it at the end. Monthly payment: The CFPB notes that lease payments may be lower than loan payments, but they go toward the vehicle’s depreciation during the lease plus rental charges, not toward ownership. Term length: The CFPB says a typical auto loan runs three to seven years, while a typical lease runs two to four years. Mileage and wear When you own a vehicle, you can drive it as far as you want, although high mileage lowers its trade-in or resale value. Leases are different. The Federal Trade Commission (FTC) says the annual mileage limit in most standard leases is 15,000 miles or less, and the CFPB gives a range of 10,000 to 15,000 miles per year. Going over the limit usually means a per-mile fee when you return the vehicle, and a higher limit will probably raise the monthly payment. Leases can also charge for wear beyond what the lessor considers normal, and the CFPB notes that the leasing company usually decides what counts as excessive. A simple test: estimate how many miles you drive in a year. If you are close to or above a typical lease limit, buying may fit better, or you would need to price a lease with a higher allowance. Leaving early Buying: If you end a loan early, you pay off what you still owe. If you owe more than the vehicle is worth, read our guide to trading in a car with a loan. Leasing: The CFPB warns that you may owe early termination charges and cannot simply return the vehicle and stop paying. The Federal Reserve’s leasing guide says the charge can be substantial and that the earlier a lease ends, the greater it is likely to be. Because of this, choose a lease term that matches how long you expect to keep the vehicle, rather than choosing a longer term only to lower the payment. What happens at the end Buying: You keep the vehicle after the loan ends, or you sell or trade it when you want something new. Preparing your trade-in can help at that point. Leasing: You return the vehicle and pay any end-of-lease fees, or buy it if your lease includes a purchase option. Check the lease paperwork for the purchase terms before you sign. Questions to ask before you choose How many miles do I drive in a typical year, and could that change? How long do I usually keep a vehicle? Do I want to own it long term, or return it and start over? If I lease, what are the mileage limit, the excess-mileage fee, the wear standards and the early termination terms? If I buy, what are the loan term and interest rate, and how will they affect the total cost? The FTC cautions that lower monthly loan payments often come from longer terms and higher interest rates, which raise the overall cost. The CFPB also notes that lease terms are negotiable and that comparing several offers can help. Review the full lease document so you know what you would be paying for the whole agreement, not just the monthly figure. Keep reading If you are still deciding between new and used, see our new vs used Chevrolet guide. If you are choosing a body style, our Chevy SUV buying guide is a good next step. Talk it through at Dial Chevrolet Browse new inventory Browse used inventory Value your trade-in Schedule service Contact Dial Chevrolet Sources CFPB: Leasing versus buying a car CFPB: What is a lease? FTC: Financing or leasing a car Federal Reserve: Keys to Vehicle Leasing, end-of-term costs Federal Reserve: Leasing vs. buying, mileage Published by Dial Chevrolet, 6603 S Western Ave, Chicago, IL. General education only; not legal or financial advice. Lease and loan terms vary by contract. This guide does not list prices, payments or offers.

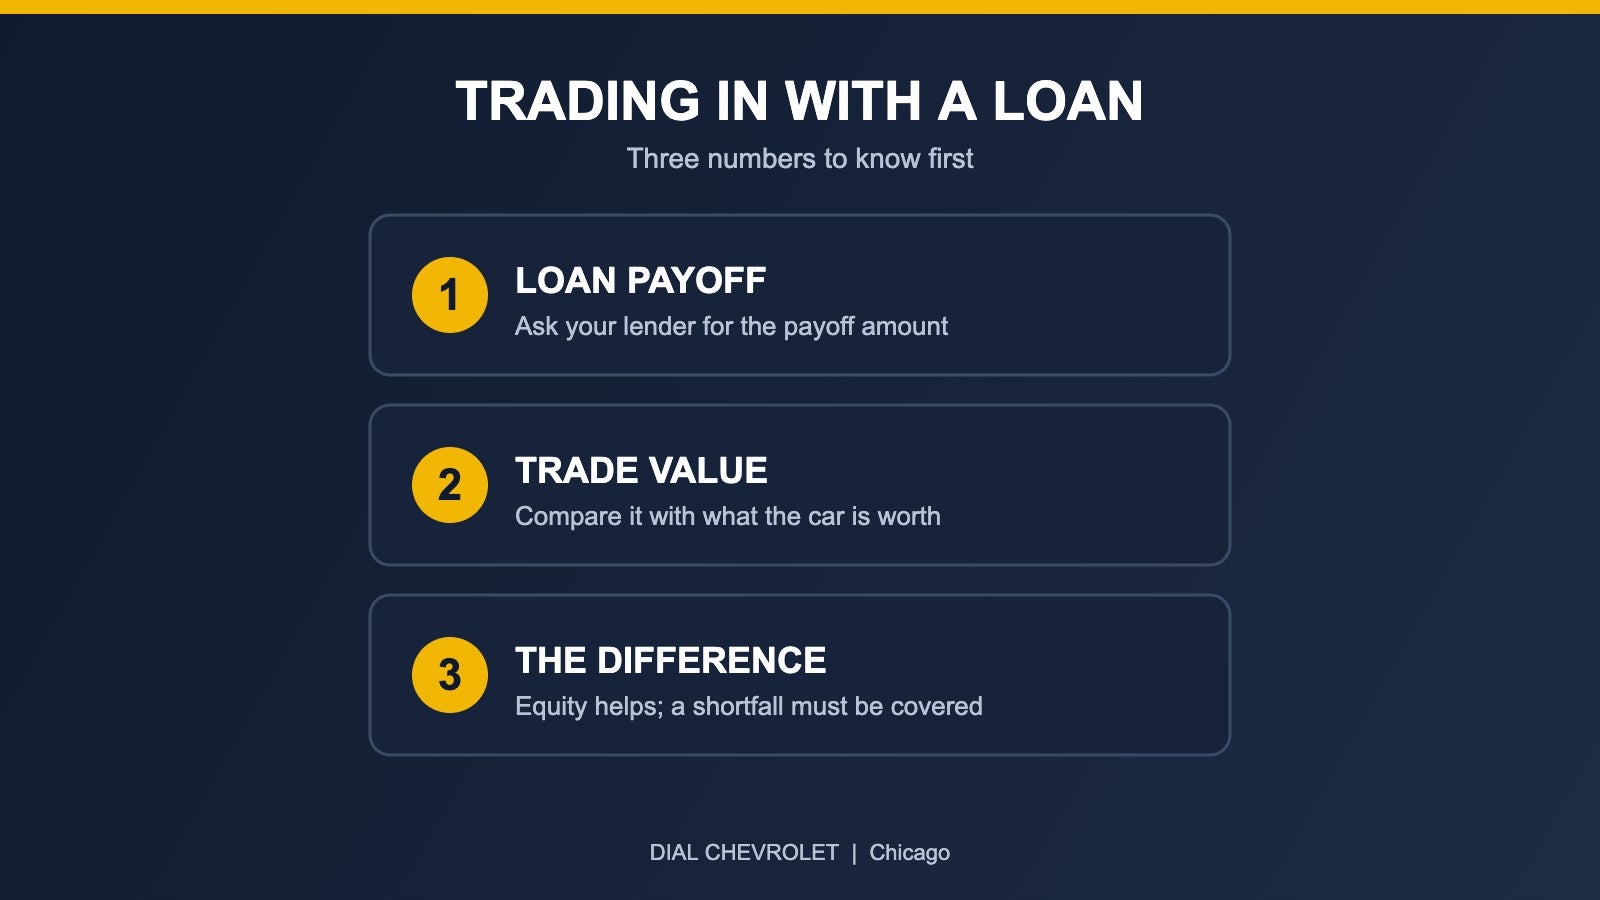
Trading in a car with a loan graphic: loan payoff, trade value and the difference

Trading In a Car You Still Owe Money On: How Payoff and Equity Work

Short answer: Yes, you can trade in a car you still owe money on. What matters is the gap between your loan payoff amount and what the car is worth. If the car is worth more than you owe, the difference works in your favor. If you owe more than the car is worth, that shortfall is called negative equity, and it has to be paid one way or another, often by adding it to the new loan. Step 1: Get your payoff amount Your payoff amount is what it would take to close the loan today. The Consumer Financial Protection Bureau (CFPB) notes it can differ from the balance on your statement because of how interest is calculated and any outstanding fees. Ask your lender for a payoff quote, and ask whether the loan carries a prepayment penalty. Your lender can also tell you which department confirms that the loan has been closed once it is paid. Step 2: Find out what the car is worth The FTC suggests checking value guides such as NADA Guides, Edmunds and Kelley Blue Book before you negotiate. The CFPB adds that you can compare trade-in estimates from several dealers and look at similar vehicles listed for sale locally. Our guide to preparing your Chevrolet for trade-in covers paperwork, cleaning and what to bring. Step 3: Compare the two numbers Trade value is higher than the payoff: You have positive equity. The dealer pays off the lender, and the remaining value goes toward your next vehicle. The CFPB advises making sure your existing loan is fully repaid before you take on a new one. Trade value is lower than the payoff: You have negative equity. The shortfall does not disappear. If you have negative equity The FTC says negative equity is common because most vehicles lose value over time, and it points out several things to know. It does not vanish: Some dealers advertise that they will pay off your loan no matter what you owe. The FTC warns that such promises can be misleading, because the dealer may roll the difference into your new loan, take it from your down payment, or both. Rolling it over costs more: A bigger loan means you pay interest on the old shortfall as well as on the new vehicle. The CFPB notes this can raise your monthly payment and total cost. You have other options: The FTC suggests waiting until you have positive equity, for example by making extra payments on the current loan, or trying to sell the car yourself, since a private sale may bring more than a trade-in. Selling privately still requires paying off the lender to release the title, so ask your lender how that works. Ask directly: If you proceed, ask how the negative equity is being treated and where it appears in the paperwork. Questions to ask before you sign What is the trade-in value, and how was it determined? Is the payoff to my lender in writing, and who sends it and when? Is any negative equity included in the amount financed? If so, how much? What is the total amount financed, the finance charge and the length of the loan? The FTC also suggests negotiating the price of the new vehicle first and bringing up the trade-in afterward, so the seller does not adjust the price to offset a generous trade-in offer. Before you sign a financing contract, the dealer must give you certain disclosures about the cost of the credit, so read them carefully. Where to go from here If you are also deciding between a new or used vehicle, our new vs used Chevrolet guide explains the trade-offs. Value your trade-in at Dial Chevrolet Value your trade-in Browse new inventory Browse used inventory Schedule service Contact Dial Chevrolet Sources FTC: Auto trade-ins and negative equity FTC: Financing or leasing a car CFPB: How to trade in your car Published by Dial Chevrolet, 6603 S Western Ave, Chicago, IL. General education only; this is not legal or financial advice. Your payoff, trade value and financing depend on your own loan and vehicle. This guide does not list prices or offers.

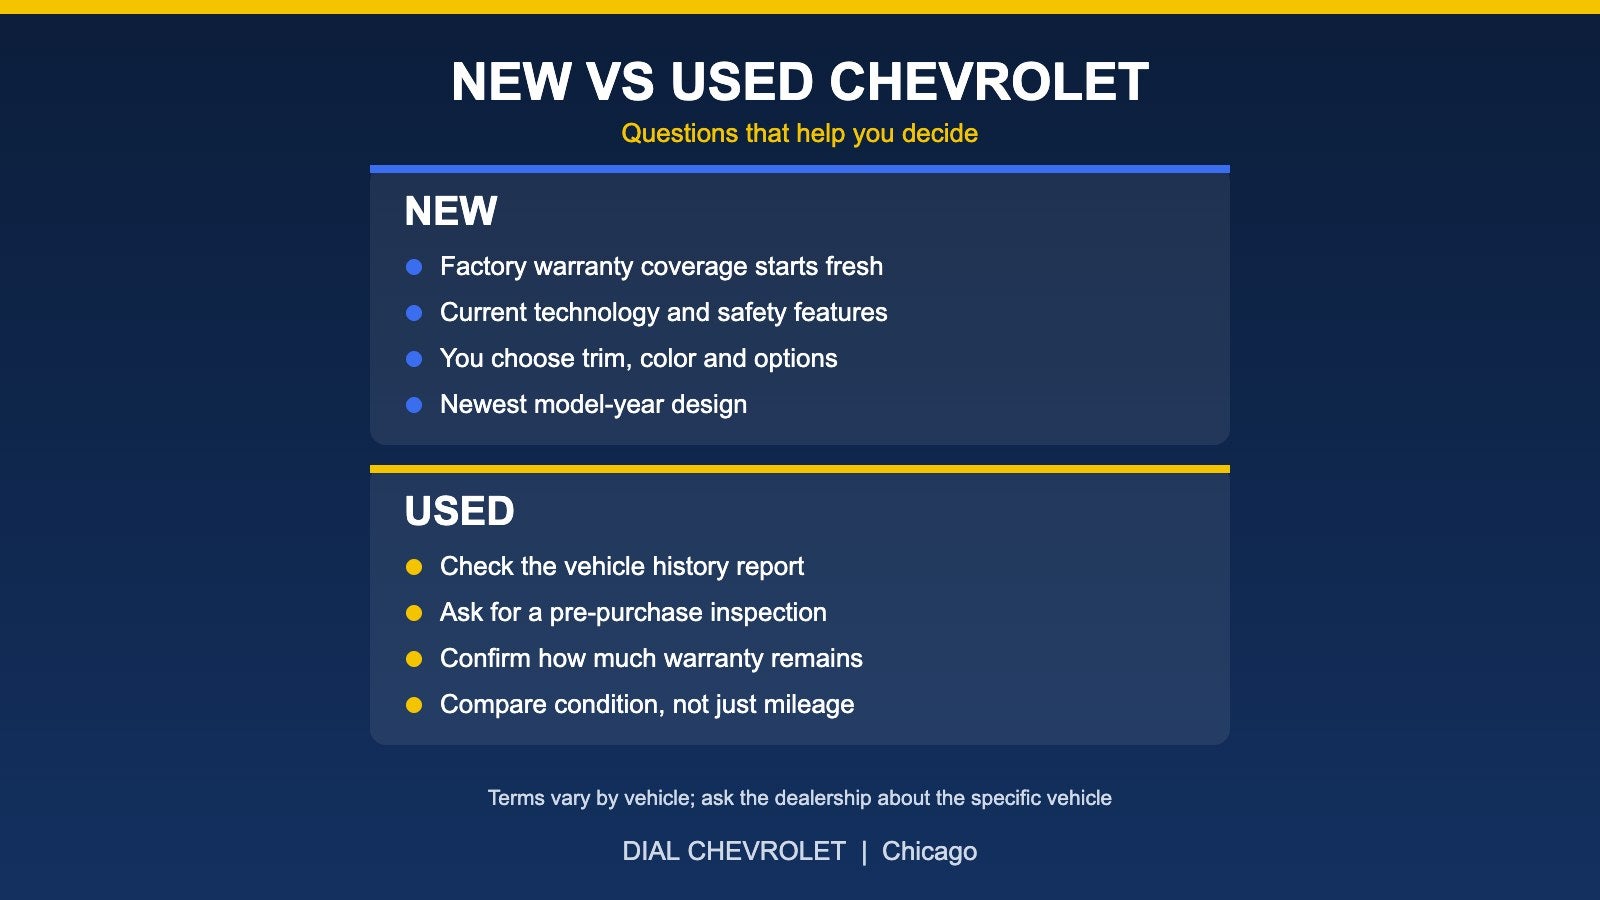
Side-by-side questions to consider when deciding between a new and a used Chevrolet

New vs Used Chevrolet: How to Decide Which Is Right for You

Short answer: a new Chevrolet gives you a fresh factory warranty and the current model-year features, while a used Chevrolet gives you more variety and the chance to choose a vehicle that has already been driven and documented. Neither is automatically better. The right choice depends on how long you plan to keep the vehicle, what you need it to do, and how comfortable you are checking its history. What a new Chevrolet gives you A fresh factory warranty. Chevrolet describes its new-vehicle coverage as typically 3 years or 36,000 miles of bumper-to-bumper protection and 5 years or 60,000 miles on the powertrain, though other durations can apply to specific vehicles. Check the warranty booklet for the exact model you are considering. Current features. A new vehicle carries the latest available technology and driver-assistance equipment for its model year. Your choice of build. You can pick the trim, color and options you want rather than working with what a previous owner chose. A known history. It has not had a previous owner, so there is no prior use to investigate. What a used Chevrolet gives you More range of choice. Used inventory can include earlier model years, different trims and vehicles that are no longer built, so there may be a closer match to what you want. A documented past. You can review a vehicle history report and ask for service records. Remaining coverage may exist. Chevrolet states that its new-vehicle powertrain and bumper-to-bumper warranties are transferable to later owners. How much coverage is left depends on the vehicle’s original in-service date and mileage, so ask the dealership to confirm it for the specific vehicle. Questions to ask before you decide How long do I plan to keep this vehicle? How many miles will I drive each year? Do I need specific features, such as advanced safety technology, a particular towing capability or a certain seating layout? Do I want to choose the exact trim and options, or am I flexible? If I buy used, can I see the history report, the service records and the inspection results? What coverage still applies to this specific vehicle, and what does it include? Do your homework on a used vehicle When you look at a used Chevrolet, ask for the vehicle history report and any service records. Take a test drive, check the tires and the interior, and look for warning lights. If you are unsure about the condition, an independent pre-purchase inspection can add confidence. Certified pre-owned programs exist, and their requirements and benefits differ by program and by dealership, so ask what applies to the vehicle you are looking at. Think about your trade-in too If you have a vehicle to trade, having your paperwork, loan details and records ready can make the process easier. Our trade-in preparation checklist walks through what to gather. Match the vehicle to the job Whatever you choose, start with what you need the vehicle to do. If you are weighing trucks, see our guides on Silverado 1500 trim levels and how payload works. If you are comparing SUVs, our Chevy SUV buying guide explains the lineup by size. See what is available Browse new Chevrolet inventory or used vehicles, get an idea of what your current vehicle is worth on our trade-in page, or contact our team with questions about a specific vehicle. Sources Chevrolet: Warranty Chevrolet: Performance vehicle FAQs (warranty transferability) Published by Dial Chevrolet, 6603 S Western Ave, Chicago, IL. Warranty terms vary by vehicle and model year. This guide does not list prices or offers.

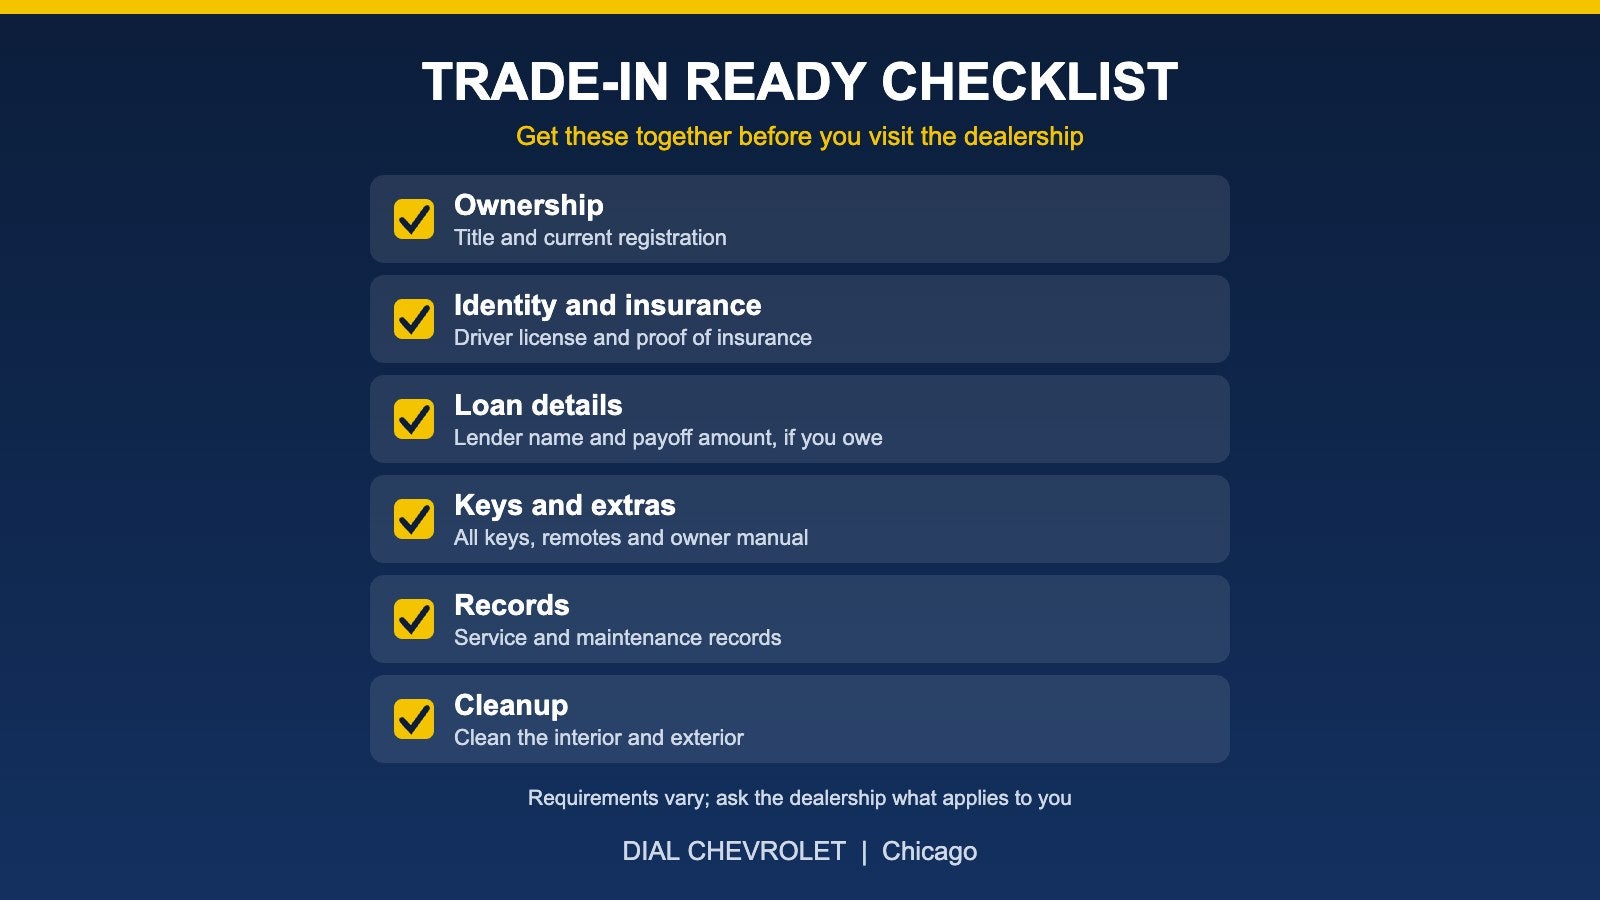
Six-item trade-in ready checklist: ownership, identity and insurance, loan details, keys and extras, records and cleanup

Trade-In Preparation Checklist: What to Do Before You Visit the Dealership

Short answer: before you bring a vehicle in for a trade-in appraisal, gather your paperwork, find out whether you still owe money on it, collect your keys and records, and give it a good cleaning. None of this is complicated, but having it ready makes the visit faster and gives you a clearer picture of where you stand. Gather your paperwork first Requirements can vary by vehicle and by situation, so ask the dealership what it needs for yours. These are the items most people are asked for: The title, if you own the vehicle outright, or the lender’s details if you still have a loan Your current registration A valid driver license Proof of insurance Any service and maintenance records you have kept Know what you owe If you still have a loan, contact your lender and ask for the payoff amount. The payoff is what it would take to close the loan, and it can differ from the balance on your latest statement. Knowing it helps you understand whether your vehicle is worth more than you owe (positive equity) or less (negative equity). If you owe more than the vehicle is worth, that gap does not disappear. It may be rolled into a new purchase, which can raise what you finance. It is worth asking about before you decide, and our team can walk through it with you. Collect keys, remotes and manuals Bring every key and remote you have. A missing second key fob is one of the things an appraiser may note. If you still have the owner’s manual and any accessories that came with the vehicle, bring those too. Pull together your service records Oil changes, tire rotations, brake work and other documented maintenance show that the vehicle was looked after. If you are not sure how often an oil change is due, our guide on how often to change oil in a Chevy explains how the oil life system works. Clean it, but keep repairs in perspective A clean interior and exterior makes a better first impression and lets the appraiser see the vehicle clearly. Remove personal items, clear out the glove box and trunk, and vacuum the seats and floors. Small fixes, such as a burnt-out bulb, can be worth handling. For larger repairs, it is generally smart to ask before spending money, since the cost of a major repair does not always come back in the appraisal. Do your homework on value Check what similar vehicles are listed for in your area Be ready to describe condition honestly, including any warning lights, dents or interior wear Consider getting more than one offer so you can compare What happens at the appraisal An appraiser will typically look over the exterior and interior, check the mileage, review the vehicle’s history and condition, and often take it for a short drive. Having your records and honest notes ready keeps the process smooth. Ready to find out what your vehicle is worth? Start with our trade-in page, browse new Chevrolet inventory or used vehicles, or contact us with questions. If your vehicle is due for service before you trade it in, you can schedule a service appointment. Sources Experian: When should you trade in a car? AAA: Preparing your car for trade-in Cars.com: How should I prep my car for sale to a dealer? Published by Dial Chevrolet, 6603 S Western Ave, Chicago, IL. Trade-in requirements and values vary by vehicle and situation. This guide does not list prices or offers.

Contact Us

Fill out this form below and we'll contact you shortly
*Required Fields